Premium Card Fee Hikes Squeeze Traveling Business Owners
Contributors: Ari Page and Kayla Page|9 min read
Disclosure: Fund&Grow may earn a commission from partner links in this article. Partner relationships do not influence the information or analysis provided.
For a business owner who travels regularly, a premium card can make long airport days easier and help offset some travel costs. Over the past year, though, rising premium card fees and tighter lounge rules have changed how far those benefits stretch. The shift is sharpest for accounts that include employees, guests, and additional cardholders.
American Express and Chase both raised the price of their flagship cards during that time. Each paired its increase with new credits and perks tied to specific kinds of spending. For entrepreneurs who balance travel with inventory, equipment, and payroll, the question is how much of that package fits the way the business already operates. A clear answer starts with how card points and perks are calculated, since that math shapes the value behind every annual fee.
Key Takeaways
- The annual fee is only part of the cost. Employee cards and lounge access can add recurring charges, especially for owners with several travelers.
- More benefits do not automatically mean more savings. Statement credits and travel perks deliver value when they match spending and trips the business already plans.
- A card’s value can change after signup. Since benefits shift over time, review costs and perks before each renewal.
How Are Credit Card Points and Perks Calculated?
Points are earned by spending category
Premium cards award points for every dollar spent, and the rate changes based on what the business buys. Purchases in a card’s bonus categories earn extra points per dollar, while everything else earns a base rate, usually one point per dollar. The Amex Business Platinum, for example, earns 2 points per dollar on eligible purchases in key business categories. It also earns 2 points per dollar on single purchases of $5,000 or more, up to $2 million a year (Source: American Express; One Mile at a Time). A business that spends heavily in those categories builds points faster than one whose spending falls mostly outside them.
A point’s value depends on how it is redeemed
Unlike cash, card points change in value depending on how an owner redeems them. Common options include a statement credit, a booking through the card's travel portal, or a transfer to an airline or hotel program. For example, a business that puts $10,000 of eligible spending on a card earning 2 points per dollar collects 20,000 points. At one cent per point, those points cover $200 in costs. A strong airline redemption may stretch the same balance further, while lower-value options, such as some gift card or merchandise redemptions, may cover less than $200.
Credits and perks are counted at full price
Beyond points, a card’s advertised value also includes statement credits, lounge access, and travel protections. When issuers add up that value, they count each credit at its full dollar amount, as if the cardholder uses every one of them each year. A $200 airline credit, for example, saves the business $200 only when it covers a flight or fee the business would have paid for anyway. A credit that goes unused, or that only gets used because it is there, adds less real value than the advertised total suggests.
What Are Owners Paying for the Updated Cards?
Higher fees deserve a closer look
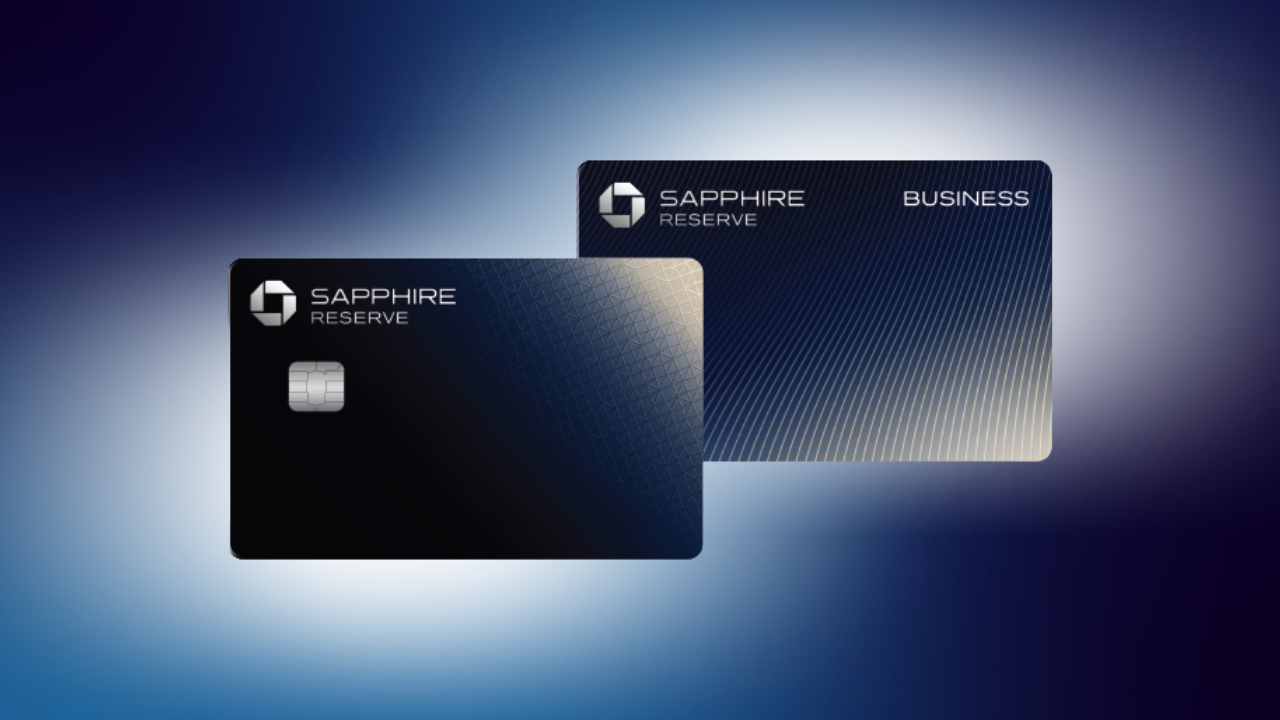
In June 2025, Chase raised the personal Sapphire Reserve’s annual fee to $795 and launched a Sapphire Reserve for Business at the same price. American Express followed in September 2025, raising the Business Platinum annual fee from $695 to $895 while adding new statement credits and higher points earning in key business categories.
$895
American Express’s annual fee for the Business Platinum Card
$795
Chase’s annual fee for the Sapphire Reserve and Sapphire Reserve for Business.
$125
Capital One’s optional yearly lounge fee per additional Venture X cardholder, up to four.
$400
American Express’s annual fee per Employee Business Platinum Card.
Sources: American Express · Chase · Capital One
Both issuers point to the value of their benefits to explain the higher prices. Chase values the personal card’s benefits at more than $2,700 a year and the business card’s at more than $2,500 (Source: Chase). Chris Reagan, President of Branded Cards at Chase, described both cards as built around the way cardmembers live and spend.
“Both cards offer incredible rewards and benefits centered on our cardmembers’ lifestyles…”
— Chris Reagan | President of Branded Cards, Chase
Advertised value depends on actual use
Like other advertised totals, Chase’s figures count every credit at full value, so the savings a business actually sees depend on which credits fit its spending. A frequent flyer may get full use of travel credits, airport lounges, and booking protections. An owner who mostly drives to job sites or flies a few times a year may use only a small share. For that reason, the renewal decision comes down to how much the business actually travels and spends, measured against the fee it pays to keep the card.
The purpose of the account matters as much as the perks
Travel perks are only one reason a business opens a credit card. When the goal is funding an equipment purchase or covering regular operating expenses, the comparison shifts toward interest, fees, available credit, and how quickly the balance can be repaid.
The business’s credit profile shapes that comparison too, since issuers often review business and personal credit when setting approval and terms. A service such as Nav Prime lets owners monitor their business and personal credit reports from several major bureaus in one place, which makes it easier to know where the business stands before applying for a new card.
For many owners, the simplest way to avoid paying for unused perks is to start with cards that charge no annual fee at all. That is why Fund&Grow’s coaching centers on business credit cards with $0 annual fees. A card without a yearly fee leaves no recurring charge to justify, although interest and other card fees still matter when comparing total costs. For businesses that travel often, a premium card may still serve a separate purpose, which makes it worth looking closely at what those cards now cost to keep.
How Do Lounge Changes Affect a Traveling Team?
Access now depends on who is traveling
Capital One now lets primary cardholders add lounge access for up to four additional Venture X or Venture X Business cardholders at $125 each per year. For a business that equips four employees, that comes to $500 a year in addition to the card’s annual fee and the cost of the trips themselves.
Whether this change counts as a loss or a gain depends on which version of the card a business carries. Additional cardholders on the personal Venture X lost the free lounge access they had before. Employee cards on the Venture X Business never included lounge access, so business accounts gained a paid option they did not previously have.
Consider a sales team that spends several hours in airports each month. For those employees, lounge access can provide a place to answer email, take calls, or eat between flights. An employee who flies only a few times a year, or who travels through airports without a participating lounge, may get little use from the same $125 charge. A quick look at each employee’s travel schedule can help an owner decide which cards are worth the added lounge fee.
Guest rules can limit how a benefit works in practice
Amex’s Centurion Lounge policy now requires guests to be booked on the same flight as the cardholder, and travelers on a connection can enter no earlier than five hours before their next departure. At U.S. Centurion Lounges, adult guests cost $50 each, while cardholders who spend $75,000 in a calendar year can bring up to two guests per visit at no charge. Because rules can vary by location, it helps to check the policy before each trip.
For owners who travel with employees or clients, the same-flight rule changes how the lounge can be used. A consultant flying out with a client on the same itinerary can still bring them in as a guest. When the two are booked on separate flights, though, the lounge is no longer an option for a quick meeting before departure. As a result, the benefit works best for owners who book the same flights as the people they travel with.
What Happens When Points Transfer Differently?
Transferring points to an airline program adds another step to the math, because each transfer happens at a set rate. Capital One miles now convert to Emirates Skywards at 1,000 to 750, and Amex Membership Rewards points convert to Cathay Pacific Asia Miles at 1,000 to 800. At those rates, an award flight that costs 60,000 airline miles would take 80,000 Capital One miles or 75,000 Amex points to book.
A transfer can still make sense when the seat is available and the total cost is reasonable. Taxes, fuel surcharges, and the number of miles required all shape that cost alongside the transfer rate. Since transfers usually cannot be reversed, checking the specific flight before moving any points helps an owner avoid converting points into miles that cannot be used as planned.
How Much Value Does the Business Actually Receive?
Once a business adds premium employee cards, the annual fee becomes only one part of the bill. Four Employee Business Platinum Cards cost $1,600 a year on top of the primary account’s $895 fee, bringing the total to $2,495 before any travel is booked. Owners can check whether other employee card options fit staff who travel less, to help reserve the premium version for the staff members who actually use its extra perks.
Statement credits also come with conditions that affect how much of their value a business sees. Some apply automatically after a qualifying purchase, while others require enrollment, a specific merchant, or spending within a set monthly or yearly window. Assigning one person to track enrollment and deadlines keeps those credits from expiring unused, which helps close the gap between a card’s advertised value and the savings it actually delivers.
$1,600
What American Express charges each year for four Business Platinum employee cards at $400 each, on top of the $895 primary card fee.
$2,700+
The yearly value Chase advertises for the personal Sapphire Reserve’s credits and perks, which depends on how many a cardholder actually uses.
$100 billion
Banks with more than this in assets, such as Chase and Capital One, would fall under the Credit Card Competition Act.
Sources: American Express · Chase · Official bill text
Could Swipe Fee Legislation Ease Costs for Businesses?
Owners who accept cards from customers face a separate cost: swipe fees, the charge for processing each card sale. On January 13, 2026, Senators Roger Marshall and Dick Durbin reintroduced the Credit Card Competition Act as S. 3623 (Source: Congress.gov). The bill would require banks with more than $100 billion in assets to offer a second, unaffiliated network on their credit cards, and its sponsors say that competition would lower swipe fees for small businesses (Source: Office of Sen. Dick Durbin).
Opponents in banking warn the bill could weaken security and reduce card rewards, so the outcome for cardholders remains uncertain. As of fall 2026, the bill had not advanced beyond introduction.
How Can Owners Decide Whether a Premium Card Still Fits?
Before each renewal, add up the annual fee, employee card fees, and lounge charges, then compare that total with the credits and perks the team actually used over the past year. That comparison shows whether a premium card still matches the way the business travels, or whether the same money would do more for payroll, materials, or client work. For owners weighing that decision alongside other financing needs, Fund&Grow’s coaches can walk through how business credit cards with $0 annual fees fit into the plan.
About the Authors
Ari Page
Read bio
Ari Page is the Founder and CEO of Fund&Grow, a business credit consulting company he started in 2007. Over nearly two decades, he has helped more than 35,000 entrepreneurs secure over $2.1 billion in total business funding. His expertise in business credit cards has made him a trusted resource for entrepreneurs, real estate investors, and small business owners across the country. All business credit cards require a personal guarantee. He is the author of “Fund&Grow: Easy & Affordable Ways to Get Money for Your Business” and regularly shares insight on entrepreneurship, business strategy, and what it actually takes to build a financially resilient business.
Kayla Page
Read bio
Kayla Page is a Marketing Coordinator at Fund&Grow with more than two years of experience at the company. Her background as a Client Success Advocate gives her firsthand insight into the business credit process and the questions entrepreneurs face when exploring funding. She contributes to Fund&Grow News, covering funding options, business planning, market trends, and economic developments affecting small businesses. Her writing connects these topics to practical considerations for managing costs, evaluating opportunities, and planning for growth.
Methodology and Disclosures
This article draws on issuer materials, published reporting, and government records available as of October 29, 2026. Issuer benefit values are promotional estimates, and actual savings depend on how each benefit is used. Fund&Grow provides coaching and education, does not lend money directly, and focuses its application support on cards with $0 annual fees. Issuer charges and Fund&Grow service fees may apply, applications involve hard credit inquiries, and approval and terms depend on the issuer. Fund&Grow may earn a commission from partner links in this article. Most business credit cards require a personal guarantee.
Fund&Grow in the News
Read our latest press coverage and media features.
Sources
- American Express. “There’s Nothing Like Platinum: American Express Unveils Updated U.S. Consumer and Business Platinum Cards.” September 18, 2025. Business Platinum annual fee, points earning rates, statement credits, and enrollment requirements.
- Chase. “The Most Rewarding Cards Are Here: The New Chase Sapphire Reserve and Introducing Chase Sapphire Reserve for Business.” June 23, 2025. Annual fees, advertised benefit valuations, and executive remarks.
- AwardWallet. “Platinum Card and Business Platinum Overhaul.” September 18, 2025. Employee Business Platinum Card fee.
- Capital One. “Airport Lounge Access Policy Guide.” Additional cardholder lounge access fee.
- Capital One. “Airport Lounge Terms.” Last updated July 8, 2026. Additional cardholder access rules for Venture X and Venture X Business.
- One Mile at a Time. “Big Capital One Venture X Lounge Access Changes Live: Here’s What’s New.” Lounge access before and after February 1, 2026, for personal and business cards.
- American Express. “Access to The Centurion Network.” Guest fees, same-flight requirement, connection access, and spending conditions.
- Emirates. “Capital One: Emirates Skywards Partner.” Capital One miles conversion ratio.
- American Express. “Membership Rewards Point Transfer.” Cathay Pacific Asia Miles transfer ratio.
- Congress.gov. “S. 3623: Credit Card Competition Act of 2026.” Introduction, sponsors, and legislative status.
- U.S. Government Publishing Office. “Credit Card Competition Act of 2026: Introduced Bill Text.” Network requirement and $100 billion asset threshold.
- Office of Sen. Dick Durbin. “Durbin, Marshall Reintroduce The Credit Card Competition Act.” January 13, 2026. Sponsors’ statements on swipe fees.
- PoliScore. “Credit Card Competition Act of 2026 (S 3623).” Opponents’ concerns about security and card rewards.
- One Mile at a Time. “Compare American Express Cards.” Business Platinum points earning rates, including purchases of $5,000 or more.
Related Reading
Swipe or scroll for more